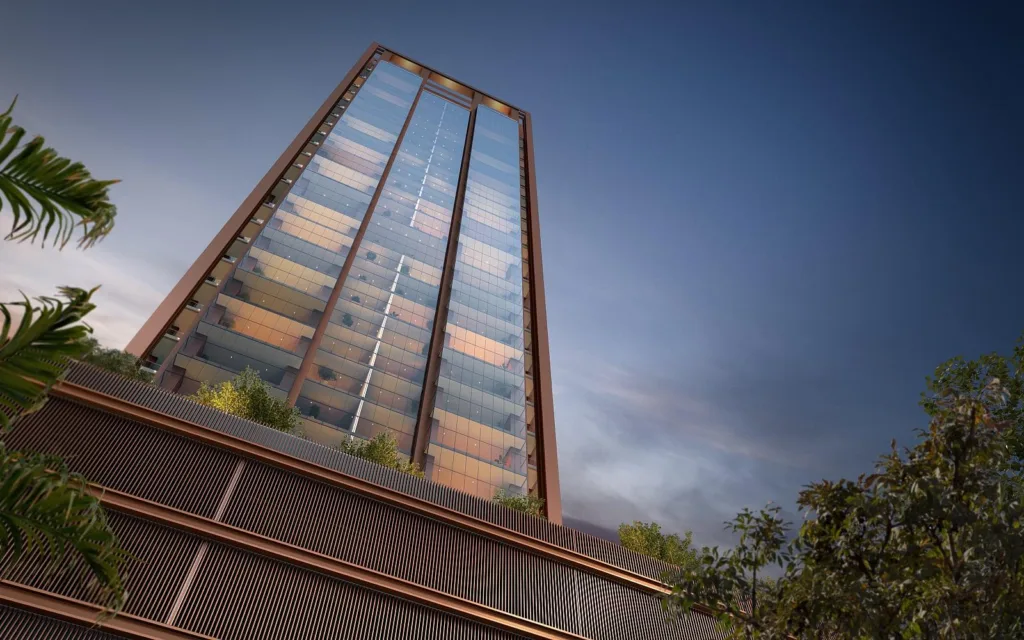
Berkeley Tower is a planned commercial office development in Business Bay, Dubai. The project is presented as a Grade A office tower by Ellington Properties, with options ranging from individual office units to half-floor and full-floor ownership.
For investors and businesses, the main questions are not limited to the launch price. They include the quality of the office product, access to major business districts, ownership costs, future leasing demand and the terms offered at launch.
The key point for buyers is that Berkeley Tower’s commercial proposition needs to be assessed using verified project specifications and confirmed sales terms. Indicative prices can help investors estimate their budgets, but the payment plan, handover date, service charges and expected rental income remain important parts of the decision.
The available project information indicates a planned launch in late October or early November 2026. As of 15 October 2026, several commercial terms are still unconfirmed. Buyers should distinguish between preliminary sales information and details formally issued by the developer.
1. Berkeley Tower at a glance
| Project detail | Current information |
|---|---|
| Project name | Berkeley Tower by Ellington |
| Developer | Ellington Properties |
| Property type | Planned commercial office tower |
| Location | Business Bay, Dubai |
| Building structure | Ground plus 62 floors |
| Office formats | Individual offices, half floors and full floors |
| Indicative price | AED 4,500–5,000 per sq ft |
| Expected launch | Late October to early November 2026 |
| Payment plan | Awaiting confirmation |
| Handover | Awaiting confirmation |
| Rental yield | No verified project-specific forecast available |
The project details above are preliminary. A separate broker-operated website lists a 50/50 payment plan, an indicative 2031 handover and a projected gross yield of 6–8%. Another page lists an EOI payment of AED 100,000 with a deadline of 16 October 2026. These terms conflict with the newer information provided for this analysis. They should not be presented as confirmed developer terms without supporting documents.
2. Why Business Bay is relevant to commercial property investors
Business Bay is one of Dubai’s established mixed-use business districts. It combines offices, residential towers, hotels, retail and hospitality facilities within reach of Downtown Dubai and the wider central business area.
For a commercial property buyer, this location offers three main advantages.
Access to business districts: Business Bay connects companies with Downtown Dubai, DIFC and other central commercial areas. This can help firms that regularly meet clients, suppliers and professional advisers across the city.
Public transport: Proximity to Business Bay Metro Station could support employees who commute by public transport. It may also help visitors reach the office without relying entirely on private vehicles.
A mixed-use business environment: Nearby residential buildings, hotels and retail outlets provide services for employees and visiting clients. This can be useful for companies that need regular access to food outlets, accommodation and meeting venues.
However, location alone does not establish an investment case. Buyers should assess the building’s access roads, parking allocation, visitor arrangements and actual walking route to the metro.
Connectivity and nearby destinations
The preliminary project information gives the following approximate travel times.
| Destination | Indicative travel time |
|---|---|
| Business Bay Metro and Sheikh Zayed Road | 1 minute |
| Bay Avenue | 2 minutes |
| Dubai Mall | 5 minutes |
| DIFC | 7 minutes |
| Jumeirah Beach | 12 minutes |
| Dubai International Airport (DXB) | 15 minutes |
These figures are indicative, not guaranteed journey times. The exact result depends on the starting point, route, traffic and whether the estimate refers to walking or driving. Buyers should confirm each route before relying on it.
For an office occupier, the practical question is how easily employees and clients can reach the building during normal working hours. A short route to the metro may offer a more consistent benefit than a drive-time estimate taken outside peak traffic.
3. Office sizes and purchase prices
Berkeley Tower by Ellington is being marketed with several ownership formats. This could appeal to owner-occupiers seeking a company headquarters and investors looking for smaller commercial units.
The preliminary rate is AED 4,500–5,000 per sq ft. The following calculations use that range to estimate the purchase budget before additional costs.
| Office format | Approx. area | Indicative purchase price |
|---|---|---|
| Individual office | From 1,250 sq ft | AED 5.63M–6.25M |
| Larger office | 2,600–2,900 sq ft | AED 11.70M–14.50M |
| Half floor | 5,250–5,750 sq ft | AED 23.63M–28.75M |
| Full floor | 10,500–11,500 sq ft | AED 47.25M–57.50M |
Price calculations use the supplied indicative areas and rate. Actual saleable areas, unit allocations and final prices require confirmation. The table excludes fees and other purchase costs.
Individual offices: a lower entry price within the project
An office starting at approximately 1,250 sq ft has a calculated base price of AED 5.625 million at AED 4,500 per sq ft. At AED 5,000 per sq ft, the same area costs AED 6.25 million.
This option may suit a small or medium-sized company that wants to own its premises. It may also appeal to investors seeking a smaller commitment than a full-floor purchase.
The main questions are the final office layout, usable area, parking entitlement and whether the space can support the intended business activity.
Half floors: space for growing companies
A half floor of approximately 5,250–5,750 sq ft requires a base budget of around AED 23.63 million to AED 28.75 million.
This format may suit companies that need several departments, meeting rooms and shared work areas. It can also provide greater control over internal planning than a smaller office.
Investors should check how the floor is divided, where the entrance sits and whether the office has independent access arrangements. The final floor plan should also clarify which areas count as saleable space.
Full floors: corporate headquarters and larger investments
A full floor of 10,500–11,500 sq ft could cost approximately AED 47.25 million to AED 57.50 million before fees.
This format may appeal to established companies that want a single address for several teams. A corporate owner may also have more freedom to plan internal spaces, subject to the building’s technical rules and approvals.
For an investor, the larger purchase price creates a different risk profile. A single vacant floor could leave a substantial amount of capital without rental income. The buyer may also need to negotiate with a narrower group of potential tenants.
The best office size depends on the intended use, not the tower’s height or the headline price per square foot.
4. What the price means after purchase costs
The preliminary information identifies a 4% Dubai Land Department (DLD) fee, administrative fees and service charges after handover.
the applicable fee basis and any additional registration costs before signing.
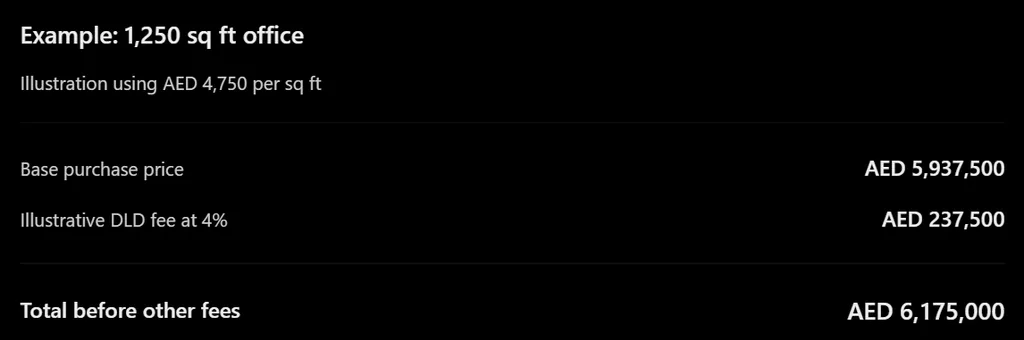
This is a calculation, not a quotation from the developer. It excludes administrative charges, financing costs, fit-out, furniture, service charges and other expenses that may apply.
Service charges and operating costs
Service charges can reduce the income retained by an office owner. The actual amount for Berkeley Tower has not been established in the information available here.
Before buying, request an estimated annual service charge per square foot and clarify what it covers. Ask about cooling, maintenance, common areas, security and parking costs. The exact cost structure will affect both owner-occupier budgets and rental returns.
Businesses should also estimate fit-out costs. An office delivered in shell-and-core condition can require substantial spending before staff can occupy it. Buyers should confirm the handover specification rather than assume the quoted price includes a completed office.
5. Building specifications and planned amenities
The supplied project details describe a G+62 tower with four to five floors dedicated to amenities.
The planned facilities include:
- A gym and dedicated yoga and Pilates studios.
- A wellness room.
- Restaurants and other food outlets.
- Twelve duplex passenger lifts and one service lift.
- An automated parking system served by two dedicated lifts.
These specifications need confirmation in the final brochure and technical documents.
Why vertical transport deserves attention
A 62-storey office tower depends on effective lift planning. Passenger capacity, lift grouping and waiting times influence the daily experience of employees and visitors.
The stated lift count is useful preliminary information, but the number alone does not establish performance. Buyers should ask for the lift specifications, passenger capacity, floor zoning and expected service levels during morning and evening peaks.
The separate service lift may help manage deliveries and building operations. Its role and permitted uses should be confirmed.
Automated parking and access
Automated parking can reduce the need for conventional parking circulation space. However, its value depends on the system’s capacity, retrieval times and operating arrangements.
Before committing funds, buyers should ask:
- How many parking spaces are allocated to each office?
- Are spaces included in the purchase price?
- What are the expected retrieval times during peak periods?
- Is guest parking available, and does it require a fee?
- What happens if the automated system needs maintenance?
For companies with frequent client visits, parking arrangements can influence day-to-day operations. These details deserve the same attention as the office floor plan.
6. Investment potential: what buyers should assess
Berkeley Tower’s proposed location and range of office sizes provide a basis for further investment analysis. They do not establish a future return.
A sound assessment should separate three factors: potential rental income, the full cost of ownership and the likelihood of finding a suitable tenant.
Rental demand and tenant suitability
Business Bay’s central location may appeal to professional services firms, regional offices, consultancies and other businesses that value access to clients and transport.
However, demand for an office depends on more than the district. Tenants compare rent, usable area, parking, building services, fit-out requirements and lease terms.
A new tower also competes with existing offices and other commercial developments. The investor should compare Berkeley Tower with completed buildings offering similar specifications and access.
Useful evidence includes current asking rents, recently signed leases, vacancy levels and the time required to secure tenants. Asking rents alone do not show the income an owner will actually receive.
Gross rental yield: a calculation
Gross rental yield measures annual rental income against the property purchase price.
Gross rental yield: a calculation.
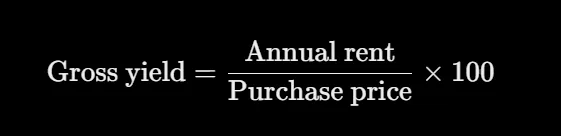
Gross rental yield measures annual rental income against the property purchase price.
Consider a hypothetical office bought for AED 6 million.
| Annual rent | Gross rental yield |
|---|---|
| AED 300,000 | 5.0% |
| AED 360,000 | 6.0% |
| AED 420,000 | 7.0% |
| AED 480,000 | 8.0% |
These figures are scenarios, not Berkeley Tower rental forecasts. They exclude vacancy, service charges, maintenance, leasing commissions and other expenses.
For example, a 6% gross yield does not mean the owner retains 6% after operating costs. A buyer should calculate net operating income and compare it with the full acquisition cost.
The most useful next step is to obtain rental evidence for comparable offices in Business Bay. That evidence should match the proposed unit size, building quality, parking provision and lease conditions as closely as possible.
Capital appreciation and resale demand
Capital appreciation depends on the eventual purchase price, market conditions, competing supply and demand for the specific office.
Large offices can appeal to corporate occupiers, but their resale market may be narrower than that of smaller units. A buyer should assess whether the unit can be divided, whether subdivision is permitted and how the saleable area is defined.
For a full-floor buyer, resale liquidity deserves particular attention. A large asset can take longer to sell if the pool of qualified buyers is limited.
No project-specific capital appreciation rate can be established from the preliminary information supplied.
7. Payment plan, handover and launch: what remains unconfirmed
The commercial terms are among the most important details still requiring verification.
| Item | Current position | What buyers should request |
|---|---|---|
| Payment plan | Not confirmed in the newer information | Official payment schedule and instalment triggers |
| Handover | Date not confirmed | Contractual completion and handover provisions |
| Expression of interest | Conflicting information across broker pages | Current EOI terms, refund conditions and deadline |
| Launch price | Indicative range only | Official unit-by-unit price list |
| Service charges | No confirmed rate supplied | Estimated annual charges and inclusions |
| Rental forecast | No verified project-specific forecast | Comparable lease evidence and independent calculations |
A separate broker website advertises a 50/50 payment plan, a 2031 handover, a projected gross yield of around 6–8% and an AED 100,000 EOI. Another page states that the launch is expected in late October or early November 2026. These differences reinforce the need to obtain the latest written terms.
Buyers should not pay an expression-of-interest amount solely because a third-party website displays a deadline. First confirm the receiving entity, the payment’s legal status, refund conditions and the document governing allocation.
8. Ellington Properties and its move into commercial offices
Ellington Properties is known for residential developments in Dubai. Berkeley Tower represents a commercial office proposition, where buyers must assess a different set of operational and investment factors.
Residential experience can provide useful evidence of a developer’s design approach and project delivery. It does not automatically establish how a new commercial tower will perform.
For Berkeley Tower, investors should review:
- The developer’s legal entity and project registration.
- The approved building plans and commercial specifications.
- Construction milestones and the contractual completion date.
- The proposed service and facilities management arrangements.
- The permitted office uses and ownership terms.
- The contractual remedies available if delivery is delayed.
This review is especially important for an off-plan commercial purchase. Buyers commit capital before they can inspect a completed office or assess the building’s operating performance.
The strongest evidence will come from project documents, relevant delivery records and independent legal review. Promotional claims should not replace these checks.
9. Who is The Berkeley Tower for?
This project have different buyers profile, but the appropriate ownership will depends on their objectives and budget.
Businesses seeking owned premises
Individual offices or half floors may suit companies that want to establish a permanent base in Business Bay. The decision should account for fit-out, staffing plans, financing and the likely duration of occupation.
Companies planning a headquarters
A full floor may provide room for several teams and shared facilities. Buyers should confirm usable space, parking and the cost of completing the interior.
Commercial property investors
Investors should compare the total acquisition cost with achievable rents in similar buildings. They should also test vacancy, leasing costs, resale demand and net yield before committing.
10. Berkeley Tower versus other Business Bay offices
The relevant comparison is not simply between buildings with similar heights. Buyers should compare completed offices and other planned commercial projects based on their intended use.
| Comparison factor | What to examine |
|---|---|
| Purchase price | Price per sq ft and total acquisition cost |
| Usable area | Net office space versus saleable area |
| Building access | Metro walking route, roads and visitor access |
| Parking | Allocated spaces, guest parking and operating costs |
| Office specification | Fit-out condition, power, cooling and technical capacity |
| Building operations | Lift performance, security and maintenance |
| Rental evidence | Achieved rents for comparable offices |
| Delivery risk | Construction progress and contractual handover terms |
| Resale market | Likely buyers for the chosen office size |
A completed building offers an advantage in one important respect: buyers can inspect the office, assess the common areas and review its operating conditions before purchase.
An off-plan project may offer a newer building and a different payment structure. However, buyers must account for construction risk, uncertainty over final specifications and the time before the asset can generate rental income.
Berkeley Tower should therefore be compared with actual alternatives using the same cost and income assumptions.
11. Frequently asked questions
What is Berkeley Tower by Ellington?
Berkeley Tower is a planned Grade A commercial office tower in Business Bay, Dubai. The preliminary information describes a G+62 building with individual offices, half floors, full floors and dedicated amenity floors.
What is the expected price of Berkeley Tower offices?
The indicative rate is AED 4,500–5,000 per sq ft. At this range, a 1,250 sq ft office would cost approximately AED 5.63 million to AED 6.25 million before fees. Final prices require confirmation.
When will Berkeley Tower launch?
The expected launch is late October or early November 2026. The final launch date remains unconfirmed in the information reviewed.
What is the payment plan for Berkeley Tower?
The newer project information does not confirm a payment plan. A separate broker page advertises 50/50 terms, but buyers should obtain the official schedule before relying on it.
When will Berkeley Tower be handed over?
A confirmed handover date has not been established from the newer information. One broker page lists 2031 as indicative, but buyers should verify the contractual date in the official sales documents.
What rental yield can investors expect?
There is no verified project-specific rental yield in the information provided. Investors should use current rental evidence from comparable Business Bay offices and calculate both gross and net yields.
What additional costs should buyers budget for?
Potential costs include the 4% DLD fee, administrative and registration charges, fit-out expenses, financing costs and recurring service charges. The applicable amounts should be confirmed for the individual purchase.
Is Berkeley Tower suitable for a company headquarters?
It may suit companies seeking a central Dubai business address and larger office configurations. The decision depends on the final layout, parking provision, fit-out cost, transport access and contractual terms.
12. Final assessment: should investors register interest?
Berkeley Tower has three preliminary features worth assessing: its Business Bay location, a range of office ownership formats and a planned high-rise commercial building.
The price range provides a starting point for budgeting. It does not establish value without comparison against competing offices, likely rental income and the full cost of ownership.
The most important outstanding details are the official payment plan, handover date, unit-level pricing, service charges and final technical specifications. investors should also verify the EOI terms before transferring any funds.
For owner-occupiers, the decision should begin with business requirements and the cost of owning the premises. For investors, the priority should be achievable rent, net yield, tenant demand and resale liquidity.
The prudent approach is to register interest if the location and budget suit your requirements, then assess the official launch pack before making a financial commitment. Until the developer confirms the terms in writing, treat the price range and building specifications as preliminary information rather than a final offer.